By Mark Lyne
Me: "Good Afternoon, how can we help you today?"
Potential Client: "Yeah – hello – I have full coverage car insurance with my current company, and I would like a quote for full coverage with you to see if I can save money on my auto insurance."
Me: "Great! What coverages are you carrying with your current company?"
Potential Client: "I don’t really know, but I think it is the state minimums"
I get this exact phone call or ones similar to it in my agency at least 3 – 4 times each week.
When I receive these calls, I will usually ask what the person is trying to accomplish by getting "full coverage". So far, I have found most believe if they are carrying the "state minimum" coverages, they are fully covered. Additionally, I have found that there are two major categories people fall into when they say "full coverage" and are looking for cheap car insurance:
Category 1 – If I have an accident, any accident, I walk away without any financial consequences at all. I am totally covered no matter what happens.
Category 2 – If somebody hits me and they do not have any insurance or if they do not have enough insurance, I will be covered for any conceivable expense to myself, my passengers, or my property as a result of their mistake.
Category 1 - I want to be covered no matter what happens
In order to answer this type of request, we must first understand that car insurance works with defined policy limits – it is helpful to understand what the numbers we see mean in the policy we purchase.
For example, in Texas, the State minimum required coverage to demonstrate financial responsibility is 20/40/15. We have all seen these numbers over and over again, but you would be surprised how many people have no idea what they mean.
Each number is in thousands and is the maximum coverage you would receive – so 20 means up to $20,000, 40 means up to $40,000, and 15 means up to $15,000. The first number is per person per accident bodily injury number in thousands. The second number is the total bodily injury per accident and the last number is the amount of property damage covered.
Our agency, through the insurance company I am appointed with offers the following levels of bodily injury liability auto coverages for non-commercial personal auto:
20/40
25/50
50/100
100/200
100/300
250/500
500/500
And the following property damage liability auto limits:
15
20
25
40
50
100
Keeping these numbers in mind – Let’s say you are carrying the Texas state minimums of 20/40/15 and that you cause an accident with $10,000 in bodily injury and $18,000 of property damage to a vehicle.
Based on your coverages, your insurance company would pay all of the bodily injury and up to $15,000 for the property damage, you would be responsible for $3,000.
Did you have full coverage?
Let’s take it to the next level with a bad accident (but definitely not the worst) – You cause an accident involving 3 other vehicles besides your own, and there are 2 people in each vehicle. We will use the same numbers as above.
6 people x $10,000 = $60,000
3 vehicles x $18,000 = $54,000
Again, if you are carrying the same coverages as listed above, 4 of the 6 people would be covered by your state minimum policy because everybody was under the $20,000 per person limit, but you maxed out your per accident bodily injury at $40,000, so you would need to take care of $20,000 of bodily injury on your own.
Next, your property damage coverage would pay for $15,000 leaving the remaining $39,000 to you. The total bill to you would be $59,000.
Did you have full coverage?
In order for you to be covered for this accident, as stated – if there is no continued litigation or lawsuits, you would need to be carrying a minimum of a 50/100/100 policy. However, if there was continued litigation or if somebody had died as a result of the accident, you might find yourself needing even more coverage than the 500/500/100 policy would provide.
Bottom line – Depending on the severity of the accident, Full Coverage under Category #1 is Fantasy.
In my next article we will discuss Category #2 – Uninsured / Underinsured Motorist Full Coverage – Fact or Fantasy?
If you are looking for more money saving tips and advice regarding car, home, life, & health insurance, visit Mark's site http://www.QuoteMyAuto.org.
Mark Lyne is a licensed Property & Casualty / Life & Health agent in Texas and has partnered with InsureMe and 2Insure4Less to provide clients with competitive quotes in order to leverage their hard earned insurance dollar as much as possible regardless of which State the client resides in.
Article Source: http://EzineArticles.com/?expert=Mark_Lyne
Thứ Ba, 27 tháng 6, 2006

Thứ Hai, 26 tháng 6, 2006
I Was In An Accident, Will My Car Insurance Rates Go Up?
By A. Chris Tijerina
You were on the phone, got distracted and before you knew it traffic had stopped, giving you no room to stop and you rear end the girl in front of you. Or, let's say you're driving along and a deer jumps out and rams into the side of your door.
Now, let's say you need to file and claim and get your car fixed. But, are your rates going to go up?
In the first case, more than likely they will depending on how much your insurance company pays out to fix both cars and medical bills if anyone was injured.
But, in the second example, since this will be a comprehensive claim your rates should not see an increase at your renewal. Unless you have a long history of hitting deer then the people from PETA will be out to get you. Or if you file a lot of small glass damage claims then your rates could be affected or you may have to pay a higher deductible for comprehensive in which case small glass damage will be less than your deductible and you will pay out of pocket.
Part 2: How long does an accident stay on my record?
Ok, so back to the example where you rear ended someone. We have already established that you are going to see your insurance rates go up. Now, we need to find out how long and how much will they go up.
State insurance boards usually allow insurance companies to charge for a accident for 3 years from the day they started charging for it. Not from the time you got into the accident. You got in the accident in December and your policy runs from October to April. Your rates won't be affected until April of the next year and the surcharge will drop off 3 years from that April.
How much will your rates go up? Are they trying to get back the money they paid out for my claim? You can usually expect a rate increase of between 20-40% on average per six months. They could go up even more if you lose some discounts you were getting, such as a claim free discount.
The increase is not a recoupment of the monies paid out by your insurance company. It is designed to charge you a premium based on the risk, or chance, that you will get into another accident in the next 3 years. You are a higher risk to the insurance company and they are able to charge you for the higher risk you present to them.
If it was based on how much the insurance company paid out then you wouldn't be able to afford it if you totaled out your 2004 Nissan Maxima at $25,000 and you had to pay that back within the 3 year surcharge period. Makes sense? Good, now get off the cell phone!
A. Chris Tijerina has over 3 years of experience in the auto insurance industry and has seen many different people deal with auto insurance related problems. http://www.insurance-for-cars.com answers many of the questions facing drivers today.
Article Source: http://EzineArticles.com/?expert=A._Chris_Tijerina
You were on the phone, got distracted and before you knew it traffic had stopped, giving you no room to stop and you rear end the girl in front of you. Or, let's say you're driving along and a deer jumps out and rams into the side of your door.
Now, let's say you need to file and claim and get your car fixed. But, are your rates going to go up?
In the first case, more than likely they will depending on how much your insurance company pays out to fix both cars and medical bills if anyone was injured.
But, in the second example, since this will be a comprehensive claim your rates should not see an increase at your renewal. Unless you have a long history of hitting deer then the people from PETA will be out to get you. Or if you file a lot of small glass damage claims then your rates could be affected or you may have to pay a higher deductible for comprehensive in which case small glass damage will be less than your deductible and you will pay out of pocket.
Part 2: How long does an accident stay on my record?
Ok, so back to the example where you rear ended someone. We have already established that you are going to see your insurance rates go up. Now, we need to find out how long and how much will they go up.
State insurance boards usually allow insurance companies to charge for a accident for 3 years from the day they started charging for it. Not from the time you got into the accident. You got in the accident in December and your policy runs from October to April. Your rates won't be affected until April of the next year and the surcharge will drop off 3 years from that April.
How much will your rates go up? Are they trying to get back the money they paid out for my claim? You can usually expect a rate increase of between 20-40% on average per six months. They could go up even more if you lose some discounts you were getting, such as a claim free discount.
The increase is not a recoupment of the monies paid out by your insurance company. It is designed to charge you a premium based on the risk, or chance, that you will get into another accident in the next 3 years. You are a higher risk to the insurance company and they are able to charge you for the higher risk you present to them.
If it was based on how much the insurance company paid out then you wouldn't be able to afford it if you totaled out your 2004 Nissan Maxima at $25,000 and you had to pay that back within the 3 year surcharge period. Makes sense? Good, now get off the cell phone!
A. Chris Tijerina has over 3 years of experience in the auto insurance industry and has seen many different people deal with auto insurance related problems. http://www.insurance-for-cars.com answers many of the questions facing drivers today.
Article Source: http://EzineArticles.com/?expert=A._Chris_Tijerina
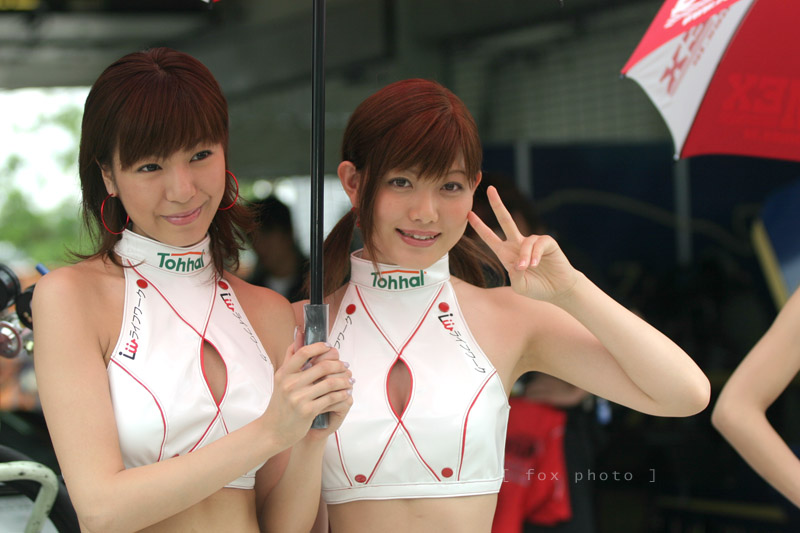
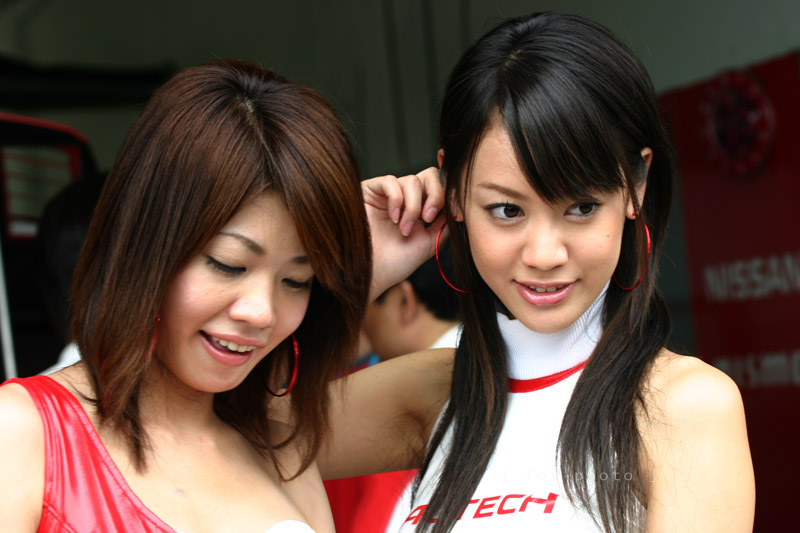
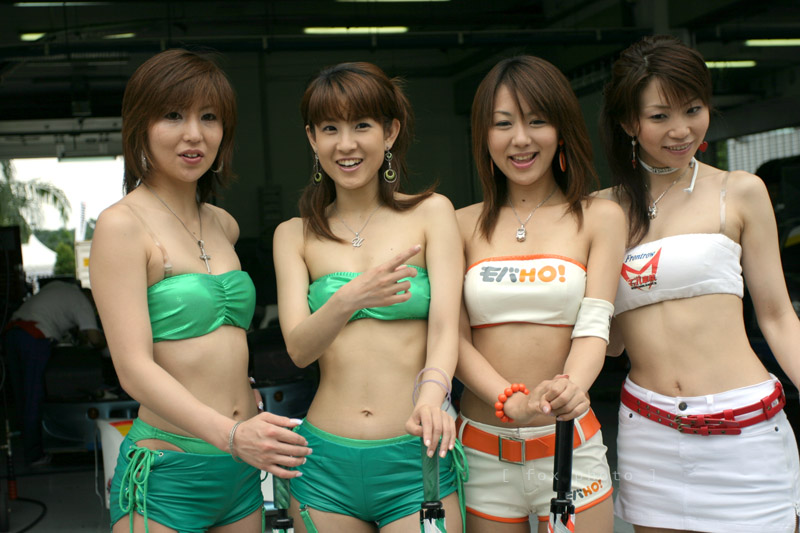


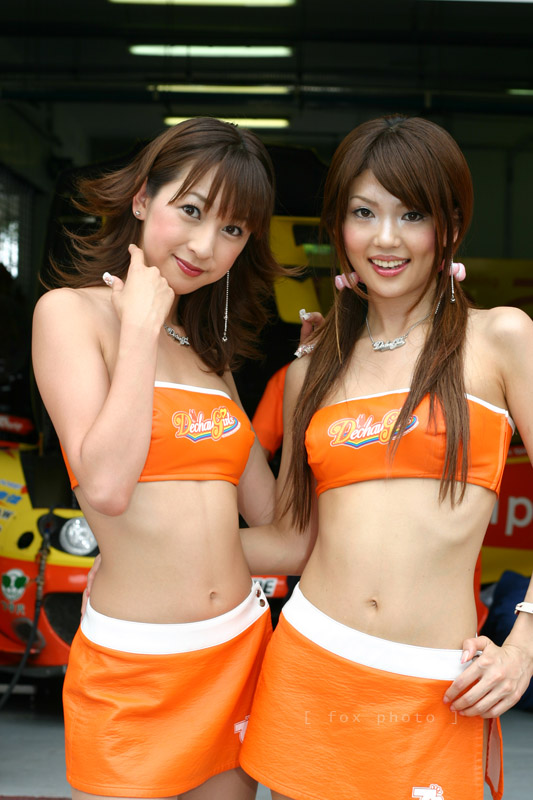
Japan GT ChampionShip Malaysia 2006

其实我不是一个赛车迷,基本上我不看F1方程式,也不看欧洲的Rally赛。可是我在念书时候看了日本的赛车动画头文字D,深深为其出神入化的技术着迷,也从此认识了一些日本街头跑车,绝对不象F1等纯粹能够在跑道上追风的那种,而是能够驾上街头拉风的霸气跑车。所以就算我不喜欢看赛车,我并不抗拒日本GT,在同事的怂恿下也就买票去看GT赛车了,当然很大部分原因是我想尝试拍摄赛车运动。
日本GT赛车是日本境内的一等一赛车盛事,马来西亚是唯一在日本境外有幸举办其中一个回合的国家。决赛开始前所有车队的GT Queen列队出场,和车手们各自站在跑道上的赛车前,旗帜和观众的喧闹声次起彼落,跑道上布满人群,拍照的摄记采访的记者进行最后赛车检查的技术人员展示迷人笑容的GT Queen沸腾的观众大家各自其司。我从远处观望,似乎看见东瀛本土的赛事时更胜的喧哗更沸腾的情绪。
技术性的东西我也不懂,这次盛事我印象最深刻的不过是不同车队赛车上艳丽的贴纸,和震耳欲聋的引擎怒吼声。最后是谁赢了我也不在乎,GT Queen的笑容依然甜美,NSX,Ferrari,Porche,RX-7,nismo Z等等赛车的美丽身影依然迷人。也许这些我通通会忘记,但体验过的经历将会被召唤。
第一名至第五名:



Chủ Nhật, 25 tháng 6, 2006
Thứ Bảy, 24 tháng 6, 2006
Free Money Saving Auto Insurance Tips
By Tim Gorman
Our money saving auto insurance tips were written for one reason - To Save You Money on your next auto insurance policy. Since in most states you are required by law to purchase a minimum amount of liability coverage we've looked for ways to save you money. Additionally many people want more than just the bare minimum in order to provide themselves with adequate protection.
The top two biggest money saving auto insurance tips are to first shop around. There are numerous providers of insurance and generally speaking you can save a great deal of money on your policy if you take the time to find the right provider.
The second biggest tip to lower your rates is to simply raise your deductable. In some cases you can reduce your annual premium by 10 percent or more if you increase your deductible by a few hundred dollars. USE CAUTION HERE: You want to make sure you can actually afford the amount that you raise your deductible to or you're no better off then before.
Additional tips include eliminating certain types of coverage from your current policy and reducing the amount of coverage you currently have. Generally this is up to each individual based on thier needs, wants and desires. You may want to consult an insurance agent before making any drastic changes to your current policy.
Other factors raising the cost of your policy include the amount of mileage you drive annually and the type of vehicle you own and operate.
Did you also know that where you live can determine rates and keeping your car in a garage can lower your rates. Cars parked in garages are less likely to be stolen, vandalized, or struck by other vehicles. Using a garage to store your car may entitle you to a slight premium reduction.
If you have multiple cars and drivers then you could qualify for a multifamily discount. Sometimes your children's insurance premium can be lowered based on their school grade point average.
Other discounts may be available if you meet certain criteria. Examples may include discounts for taking a defensive driving course, being a AAA member or staying with the same auto insurance company for a number of years. These discounts vary by company.
Finally try using an anti-theft device. This helps to reduce your insurance cost.
Thanks for taking the time to read our money saving auto insurance tips. We hope our free tips and save you some of your hard earned cash.
Timothy Gorman provides more insurance information and free money saving insurance quotes that you can research in you pajamas on his website: Best Free Insurance Quotes.
Article Source: http://EzineArticles.com/?expert=Tim_Gorman
Our money saving auto insurance tips were written for one reason - To Save You Money on your next auto insurance policy. Since in most states you are required by law to purchase a minimum amount of liability coverage we've looked for ways to save you money. Additionally many people want more than just the bare minimum in order to provide themselves with adequate protection.
The top two biggest money saving auto insurance tips are to first shop around. There are numerous providers of insurance and generally speaking you can save a great deal of money on your policy if you take the time to find the right provider.
The second biggest tip to lower your rates is to simply raise your deductable. In some cases you can reduce your annual premium by 10 percent or more if you increase your deductible by a few hundred dollars. USE CAUTION HERE: You want to make sure you can actually afford the amount that you raise your deductible to or you're no better off then before.
Additional tips include eliminating certain types of coverage from your current policy and reducing the amount of coverage you currently have. Generally this is up to each individual based on thier needs, wants and desires. You may want to consult an insurance agent before making any drastic changes to your current policy.
Other factors raising the cost of your policy include the amount of mileage you drive annually and the type of vehicle you own and operate.
Did you also know that where you live can determine rates and keeping your car in a garage can lower your rates. Cars parked in garages are less likely to be stolen, vandalized, or struck by other vehicles. Using a garage to store your car may entitle you to a slight premium reduction.
If you have multiple cars and drivers then you could qualify for a multifamily discount. Sometimes your children's insurance premium can be lowered based on their school grade point average.
Other discounts may be available if you meet certain criteria. Examples may include discounts for taking a defensive driving course, being a AAA member or staying with the same auto insurance company for a number of years. These discounts vary by company.
Finally try using an anti-theft device. This helps to reduce your insurance cost.
Thanks for taking the time to read our money saving auto insurance tips. We hope our free tips and save you some of your hard earned cash.
Timothy Gorman provides more insurance information and free money saving insurance quotes that you can research in you pajamas on his website: Best Free Insurance Quotes.
Article Source: http://EzineArticles.com/?expert=Tim_Gorman
Đăng ký:
Bài đăng (Atom)
Bài đăng phổ biến
-
我们是去吃早餐时经过的道路上,认识从远方望去是一间庄严佛寺的万佛殿,不太雄伟,像一个朴实衣装的老伯喁在一角阅读早报。后来我们吃过了早餐回到同一道公路,友人把驾驶盘一扭,我们来到了万佛殿。 “关丹最大的佛寺,有一个很漂亮的园景和湖,后面的山有很美丽的石壁。”,这是友人口中说起的万佛...
-
Auto insurance as we all know is the insurance consumers purchase for their vehicle be it a car, truck or any other automobile. The purpose ...
-
Like our life needs to be protected against the unwarned dangers, our assets too should be shielded from all kinds of damages that can happe...
-
我居住的地方有整百座五层楼组屋,分为A-G区。昨夜我和A区的居协会负责人聊天,说起日渐益下的区域治安,大家一起感叹世风日下,警察无力,摇摇欲坠的安定感。续我家被爆窃之后,这段时期陆陆续续还有其它的案件。他一一叙述: 有一位住在A区的妇女中午送女儿去学校后回家,惊然发现两个陌生华裔...
-
By David Maillie With car sales prices continuously increasing, recent hikes in gas prices, and ever present sales and state taxes on our ca...
-
 The Lincoln MKS is powered by a Lincoln absolute new 3.7-liter V-6 engine. The powertrain has been acquired from the accurate 3.5-liter V-6 ...
-
 A standard car insurance policy covers your car for so-called social, domestic and personal use, which includes everyday driving such as v...
-
 The new 2010 Lincoln MKZ mid-size auto was advised for barter who accept appear to agree Lincoln with elegant, avant-garde design, unparalle...
-
 There are a host of specialist classic car insurance companies which cater specifically for this sector of the market. However, you may als...


